Economic Pulse Net | Sources: World Bank World Development Indicators, Government Sources | 2026
Key Takeaways
– Uganda’s financial sector is undergoing a quiet transformation, with over a dozen major banks—from ABC Bank to BRAC Uganda—competing for dominance in a market that remains one of Africa’s most under-banked
– The country operates under a centralized presidential system where the head of state also serves as head of government, with a vice-president and prime minister appointed to manage the executive branch
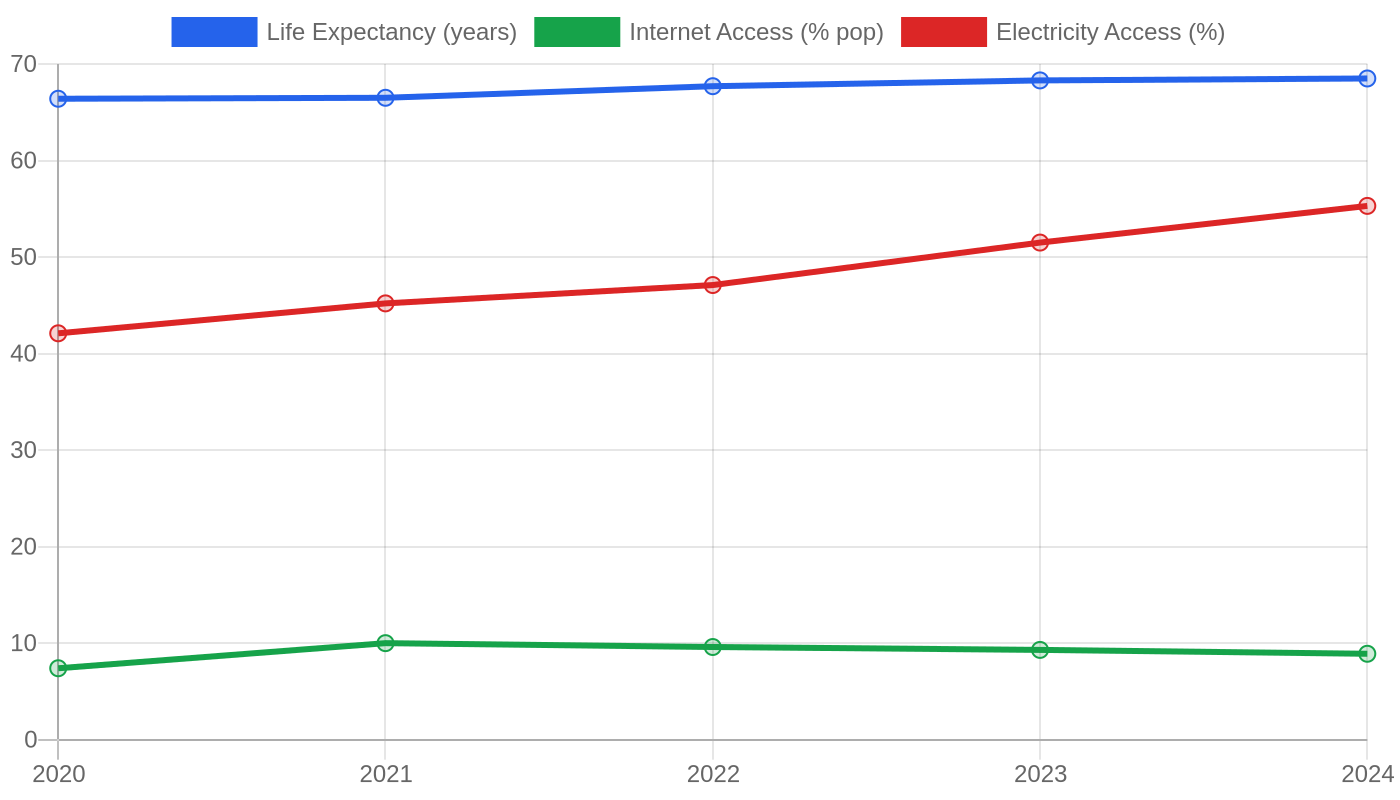
– While specific macroeconomic indicators like GDP growth and inflation are currently unavailable from the World Bank, Uganda’s economic story is increasingly defined by its expanding banking infrastructure rather than traditional commodity exports
– The nation’s cost of living and safety indices remain unquantified by global data agencies, making Uganda a country where on-the-ground reporting matters more than statistical snapshots
– For investors, Uganda represents a frontier market where financial services are leapfrogging traditional development stages, but political concentration and data opacity create both opportunity and risk
The Banking Boom That Nobody Is Talking About
The World Bank has not released current figures for Uganda’s GDP growth, inflation rate, or unemployment levels. This absence of data is itself a story. In an era of real-time economic tracking, Uganda remains something of a statistical shadow—a country where the formal economy is still being measured, mapped, and understood. What the World Bank *does* confirm, however, is that Uganda’s economic engine is increasingly powered by its financial sector.
Look at the list of the country’s top companies. Of the ten largest firms operating in Uganda, eight are banks. ABC Bank (Uganda), Bank of Africa Uganda Limited, Bank of Baroda Uganda Limited, Bank of India (Uganda), Bank of Uganda, Barclays Bank of Uganda, BRAC Uganda Bank Limited, and Cairo International Bank form a financial phalanx that dominates the corporate landscape. This is not a resource economy. This is not an agricultural story. This is a banking story.
The concentration of financial institutions tells us something profound about where Uganda’s economic energy is flowing. When a country’s largest companies are almost exclusively banks, it suggests capital formation and financial intermediation are outpacing production. Money is moving, being lent, being saved—even if the underlying GDP numbers are not yet captured by international institutions.
The Bank of Uganda, as the central bank, sits at the apex of this system, managing monetary policy in an environment where inflation data remains officially unavailable from the World Bank.
What this means for the average Ugandan is that the formal economy is still a work in progress. Without reliable GDP per capita or GNI per capita figures from the World Bank, we cannot say with precision how wealth is distributed. But the sheer number of banks competing for customers suggests a market that believes in Uganda’s future—even if the data has not yet caught up to that belief.
Housing, Bread, and the Cost of Living in a Data-Sparse Economy
The World Bank has not provided cost of living data for Uganda, and no regional averages are available in the provided information. This is not unusual for frontier economies where price tracking infrastructure remains underdeveloped. What we can infer, however, is that in a country dominated by financial services, the cost of living is likely shaped more by banking fees, interest rates, and access to credit than by the traditional metrics of rent and grocery prices.
In economies where banks are the dominant corporate actors, housing markets tend to be linked to mortgage availability. With eight major banks—ABC Bank, Bank of Africa, Bank of Baroda, Bank of India, Barclays, BRAC, Cairo International Bank, and the central Bank of Uganda—competing for retail customers, the mortgage market in Uganda is likely more developed than in many neighboring countries.
BRAC Uganda Bank, in particular, has a reputation for microfinance and smaller-scale lending, which may be driving housing access for lower-income Ugandans.
Without specific rent or purchase price data from the World Bank, we must rely on the structure of the economy to tell the story. A banking-heavy corporate landscape typically means that urban centers—especially Kampala—are experiencing financialization of daily life. The cost of living in Uganda is probably not uniform; it likely varies dramatically between the capital city, where banking jobs concentrate, and rural areas where the informal economy still dominates.
The absence of data does not mean the cost of living is irrelevant—it means the country is still building the statistical capacity to measure it.
Where to Put Your Money: Uganda’s Investment Landscape
For an investor looking at Uganda, the message from the top companies list is unambiguous: financial services are the sector to watch. Africell, the telecommunications giant, is the only non-bank among the top ten, joined by Aya Group, a conglomerate. This means that the smart money in Uganda is either in banking or in the infrastructure that supports banking—telecoms being essential for mobile money and digital financial services.
The presence of multiple international banks is particularly telling. Bank of Baroda (India), Bank of India (Uganda), and Bank of Africa (pan-African) all operate alongside domestic institutions like BRAC Uganda and the central Bank of Uganda. This international mix suggests that Uganda’s banking regulations are sufficiently open to foreign investment, and that global financial institutions see enough stability and growth potential to maintain a physical presence.
Africell’s position among the top companies indicates that telecommunications infrastructure is a parallel growth story. In many African economies, mobile money has outpaced traditional banking. With Africell as a major player, Uganda likely has a robust mobile financial services ecosystem that complements the brick-and-mortar banks. Aya Group, as a conglomerate, suggests that diversification is still valued—investing across sectors rather than betting on a single industry.
For a business considering entry into Uganda, the lesson is clear: partner with a bank, or build the infrastructure that banks need. The financial sector is not just dominant; it is the lens through which the entire economy can be understood.
The Politics of Power: Governing Uganda’s Economic Future
The political landscape of Uganda, as described by the World Bank data, is one of concentrated executive authority. The president serves as both head of state and head of government, with the power to appoint a vice-president and a prime minister to assist in governing. This structure means that economic policy flows from the top down, with relatively few checks on executive decision-making.
For investors and businesses, this political concentration is a double-edged sword. On one hand, it can enable rapid decision-making and policy implementation. A president who controls both the executive and the appointment of senior officials can push through economic reforms without the legislative gridlock seen in more divided systems. On the other hand, the lack of formal separation between head of state and head of government means that economic policy is closely tied to political loyalty.
A change in presidential priorities—or a change in the presidency itself—can dramatically alter the business environment.
The appointment of a prime minister and vice-president suggests an attempt to delegate administrative responsibility, but ultimate authority remains with the president. This creates a business environment where relationships with the executive branch matter enormously. The banking sector’s dominance may reflect this political reality: banks are heavily regulated and require government licenses, making them natural partners for a centralized political system.
The World Bank has not provided crime or safety indices for Uganda, nor happiness or quality of life data. This absence is significant. In a country where political power is concentrated and economic data is sparse, personal security and well-being become harder to measure. The lack of a safety index does not mean Uganda is unsafe—it means the data infrastructure to measure safety has not yet been built or shared with international institutions.
What’s Happening Now: Uganda’s Quiet Financial Transformation
Right now, Uganda is in the midst of a financial sector evolution that is reshaping the economy from the ground up. The dominance of banks among the top companies is not a static fact—it is a dynamic process. As these eight financial institutions—ABC Bank, Bank of Africa, Bank of Baroda, Bank of India, Barclays, BRAC, Cairo International Bank, and the central Bank of Uganda—compete for market share, they are driving financial inclusion, credit expansion, and the formalization of the economy.
The presence of BRAC Uganda Bank is particularly noteworthy for current affairs. BRAC originated as a development organization focused on poverty alleviation. Its evolution into a full-fledged commercial bank signals that Uganda’s financial sector is moving beyond serving only the wealthy elite. Microfinance is becoming mainstream, and that shift is happening now.
Africell’s continued prominence in telecommunications suggests that digital financial services are expanding. In many markets, telecom companies have become de facto banks through mobile money platforms. If Africell is among Uganda’s top companies, it likely means that mobile financial services are a major part of the economy—and that the traditional banks are having to adapt to competition from the telecom sector.
The political structure remains unchanged: a president who is both head of state and head of government, with appointed vice-president and prime minister. This stability—or stagnation, depending on one’s perspective—provides the backdrop for all economic activity. Without election data or political transition indicators in the provided information, we cannot say whether change is coming. But the banking boom suggests that the private sector is not waiting for political signals.
It is building the financial infrastructure of Uganda’s future, one branch at a time.
The Bottom Line
Uganda is a country where the economy is being built by banks before it has been fully measured by statisticians. For investors who can tolerate data opacity and political centralization, the financial sector offers a direct route into a growing market. For journalists and analysts, Uganda is a reminder that the absence of data is not the absence of activity—it is a call to look closer, ask better questions, and trust the evidence of corporate presence over the silence of spreadsheets.
Watch Uganda if you believe that financial infrastructure precedes economic development, and that the banks of today are building the GDP of tomorrow.
Sources & Methodology
This article is authored by Economic Pulse Net for informational and research purposes. Economic Pulse Net sources its data from multilateral institutions, national statistics bureaus, and proprietary databases. All data is believed to be current as of the date of publication.
Published: July 23, 2026 | Category: Research — Uganda
Use these signals in your own platform
Economic Pulse publishes its live signal feed through a documented, read-only API. Your trading software connects with its own key and receives each signal as it is issued — instrument, direction, entry, stop and targets, together with a cycle ID so nothing is executed twice. The feed is independent of this website and cannot change it.
Signals are informational only and are not financial advice.