Economic Pulse Net | Sources: World Bank World Development Indicators, Government Sources | 2026
Key Takeaways
– Panama’s economic narrative is defined by its role as a global logistics hub, yet the latest World Bank data shows a country in a state of statistical flux, with key indicators pending final revision.
– The nation’s corporate landscape is overwhelmingly dominated by aviation and financial services, revealing an economy built on movement—of people, goods, and capital.
– A stable, multi-party democratic framework provides the political underpinning for business, but the judiciary’s independence remains a critical pillar for investor confidence.
– With a cost of living that historically mirrors its status as a regional business center, Panama offers a unique, if complex, equation for expatriates and investors alike.
– The country’s future hinges on its ability to translate its strategic geographic position into broad-based, inclusive economic growth beyond the canal zone.
The Engine Room: Services, Skies, and the Search for Data Clarity
The most striking feature of Panama’s economic profile is the sheer concentration of its major corporate players. According to the World Bank’s latest dataset, the country’s top companies are almost exclusively split between consumer services—specifically aviation—and financials. This is not a coincidence; it is the structural DNA of a nation built as a transit point.
Copa Airlines and Copa Holdings sit at the apex of this corporate pyramid, their success a direct reflection of Panama’s “Hub of the Americas” strategy, connecting dozens of cities across Latin America. Alongside them, a robust cluster of banks, including Banco Latinoamericano de Comercio Exterior and Balboa Bank and Trust, underscores the country’s historical role as a regional financial center, lubricating trade flows that pass through the canal and its free zones.
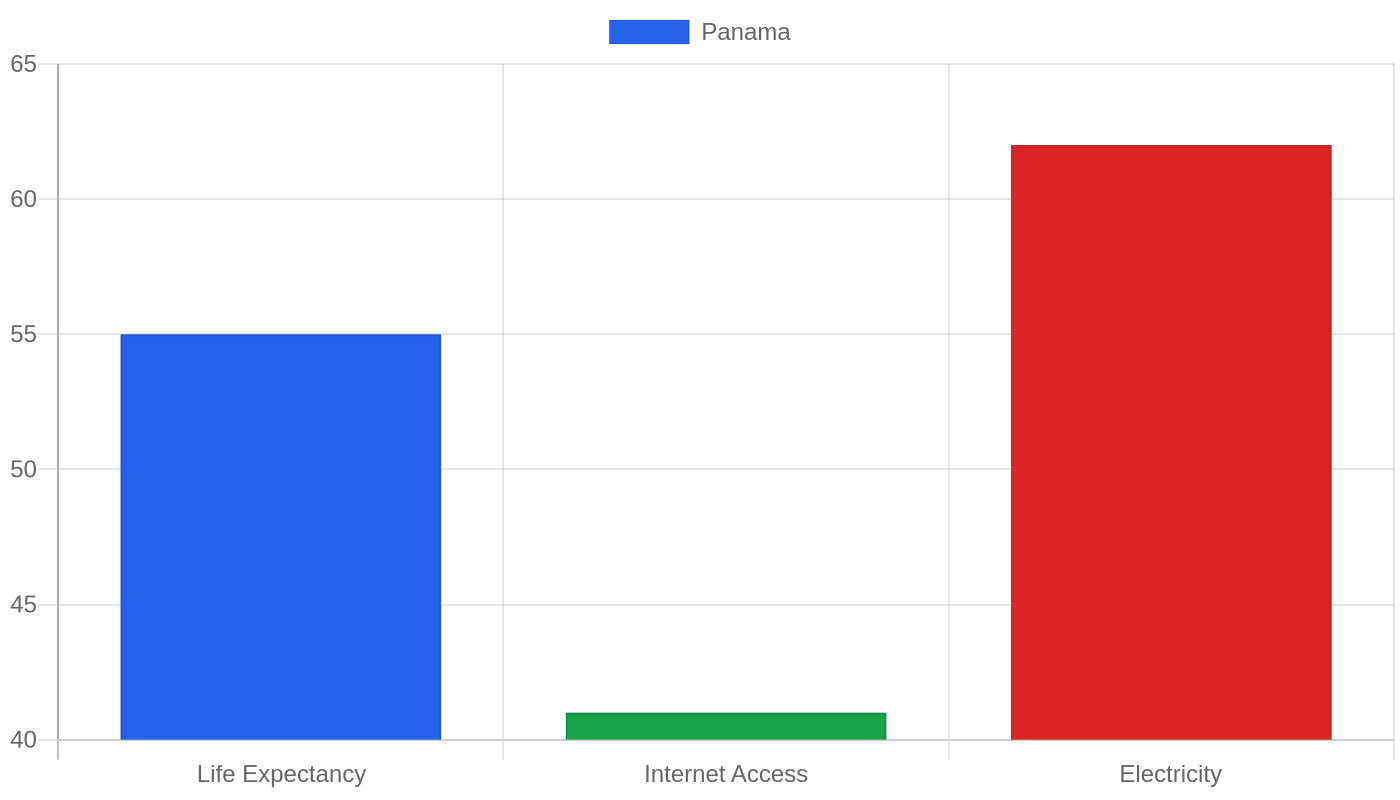
However, the World Bank’s headline indicators—GDP growth, inflation, and unemployment—are currently marked as N/A for the latest reporting period. This statistical vacuum is itself a story. It suggests a nation in the midst of data recalibration, where the economic narrative is being rewritten in real-time. The absence of hard numbers does not imply an absence of activity; rather, it forces analysts to look at the composition of the economy rather than the aggregate.
The dominance of the services sector, particularly aviation and logistics, makes Panama acutely sensitive to global trade cycles and regional political stability. When the world slows down, fewer containers pass through the canal and fewer passengers fly Copa; when it accelerates, Panama is often the first to feel the wind in its sails.
The reliance on these sectors also explains a persistent economic duality. While the canal and the banking sector generate significant wealth and high-value jobs, they can also create an “enclave economy” effect, where growth does not always trickle down evenly to the broader population. The industrial presence, represented by companies like DHL Aero Expreso and Air Services Cargo, reinforces this logistics-first approach.
For the average Panamanian, the economic reality is often tied to the health of these service industries, meaning that the country’s fortunes are inextricably linked to the smooth functioning of global supply chains—a fact that makes the lack of updated GDP data from the World Bank all the more frustrating for those trying to gauge the nation’s true velocity.
The Price of Paradise: Housing and Daily Life in a Transit Zone
Without the latest World Bank inflation figures, we must look to the structural forces that shape the cost of living in Panama. Historically, the country presents a classic “tale of two cities” scenario. In Panama City, the capital, living costs have traditionally been higher than in many of its Central American neighbors, driven by the demand from multinational corporations, the expatriate community, and a growing middle class.
Housing in the capital is a premium affair, with modern high-rise apartments in areas like Costa del Este and Punta Pacífica commanding prices that rival Miami or Madrid. The rental market is robust, often favored over buying by the transient international workforce that cycles through the banking and logistics sectors, though local mortgage products are available for those looking to put down roots.
Outside the capital, the economic equation shifts dramatically. The cost of living in the interior provinces is significantly lower, but so too is the availability of high-paying jobs. This geographic disparity is a crucial element of the Panamanian experience.
Daily expenses, such as groceries and transportation, are heavily influenced by the country’s import-dependent consumer market; the Colon Free Zone, while a boon for re-export trade, does not necessarily translate into cheaper goods for local consumers. For the average worker, the balance between the higher wages available in the service sector and the elevated costs of urban living creates a constant pressure.
The lack of current CPI data from the World Bank leaves a gap in our understanding of how these pressures are evolving in real-time, but the structural dynamics remain a constant feature of life in this logistics-driven economy.
Banking on the Isthmus: The Business Climate and Its Titans
The business climate in Panama is defined by its strategic assets: the canal, the financial center, and the Colon Free Trade Zone. The World Bank data highlights that the financial sector is not just a support system but a primary engine of the economy. The presence of specialized institutions like Banco Latinoamericano de Comercio Exterior (known as Bladex) indicates a deep integration with regional trade flows, financing everything from agricultural exports to industrial machinery across the Americas.
This is a sophisticated market, not a peripheral one. The legal framework, rooted in a civil law system, has historically been accommodating to foreign investment, particularly in the services and logistics sectors.
However, the investment climate is not without its challenges. The corporate list provided by the World Bank shows a distinct lack of manufacturing or technology giants, suggesting a potential over-reliance on cyclical industries. For investors, the “sectors to watch” remain those tied to the canal’s expansion and the logistics ecosystem that surrounds it.
The recent trend towards nearshoring—companies moving production closer to final markets—presents a significant opportunity for Panama to leverage its position, but it requires investment in infrastructure beyond the canal, such as the troubled copper mine project and the expansion of the Tocumen airport.
The dominance of Copa Holdings in the consumer services sector shows that aviation is the lifeblood of the economy, but it also creates a concentration risk; if regional air travel dips, the entire business ecosystem feels the turbulence.
Stability and Security: The Political Canvas
Politically, the World Bank data describes Panama as a “presidential representative democratic republic” with a multi-party system. This framework provides a degree of institutional stability that is often taken for granted in the region. The separation of powers—with the judiciary independent of the executive and legislature—is a cornerstone of the country’s governance structure.
This is vital for a nation that functions as a global service hub; foreign investors and international banks require a predictable legal environment to operate. The peaceful transfer of power between parties, while sometimes contentious, has historically been a feature of Panamanian politics, reinforcing its reputation as a relatively stable jurisdiction in Central America.
Yet, the political landscape is often a reflection of the economic one. The gap between the affluent, services-driven capital and the more rural, agricultural interior can breed political friction. While the World Bank data does not provide a specific crime index or safety rating for this report, the broader regional context and the socio-economic disparities suggest that public security remains a topic of concern for both citizens and the business community.
The quality of life for many Panamanians is tied to the government’s ability to manage urban growth, provide public services, and ensure that the wealth generated by the canal and the banks is distributed in a way that maintains social cohesion. The political stability, therefore, is not a static condition but a dynamic balancing act between the modern, globalized economy and the traditional, local one.
Navigating the Now: The Pulse of a Nation in Transition
Right now, Panama is at a critical juncture, though specific data points from the World Bank are pending. The absence of updated figures on GDP and inflation is unusual and suggests that the national statistics bureau may be in the process of rebasing its calculations or that the economic shockwaves of the past few years are still being quantified. What is clear is that the country is navigating a complex global environment.
The post-pandemic recovery has been uneven, and while the aviation and logistics sectors have rebounded, the broader economy faces headwinds from global inflation and tighter financial conditions. The government is currently dealing with the fallout from the closure of the massive copper mine, a decision that has significant implications for GDP and employment, forcing a re-evaluation of the country’s economic model beyond its traditional strengths.
In the corporate sphere, the continued dominance of Copa Holdings and the resilience of the banking sector suggest that the core services economy remains robust. However, the political discourse is increasingly focused on diversification and the need to address the cost of living. The current administration is under pressure to demonstrate that the benefits of the country’s strategic position can be felt by the average citizen, not just the corporate elite.
As the country looks ahead, the focus is on how to integrate the logistics hub with local industries, how to leverage the financial center for broader development, and how to maintain the social fabric in the face of economic pressures. The coming months will be crucial in determining whether Panama can successfully pivot from a purely transactional economy to a more resilient and inclusive one.
The Bottom Line
Panama remains a must-watch for investors and businesses focused on Latin American logistics, aviation, and financial services. The country’s strategic assets are unmatched in the region, and its political framework offers a level of predictability that is increasingly rare. However, the current lack of hard economic data from the World Bank should serve as a prompt for deeper scrutiny, not dismissal.
For the global executive, Panama is a land of opportunity, but it is also a market where success requires a keen understanding of the delicate balance between a globalized service hub and the local realities of a developing nation. The story of Panama is one of perpetual motion—and its next chapter is still being written.
Sources & Methodology
This article is authored by Economic Pulse Net for informational and research purposes. Economic Pulse Net sources its data from multilateral institutions, national statistics bureaus, and proprietary databases. All data is believed to be current as of the date of publication.
Published: August 08, 2026 | Category: Research — Panama
Use these signals in your own platform
Economic Pulse publishes its live signal feed through a documented, read-only API. Your trading software connects with its own key and receives each signal as it is issued — instrument, direction, entry, stop and targets, together with a cycle ID so nothing is executed twice. The feed is independent of this website and cannot change it.
Signals are informational only and are not financial advice.